Payday Loan Laws by State (2026): Limits, Fees and Status in All 50 States
By TCA Financial Editorial Team. Last reviewed: October 25, 2026.
Disclosure: TCA Financial (tcaloans.com) is not a lender and does not make credit decisions. We connect people with independent lenders and may be paid by those lenders for advertising. This guide is general information, not legal advice. Laws change, so check your state regulator (linked in the table) before you borrow.
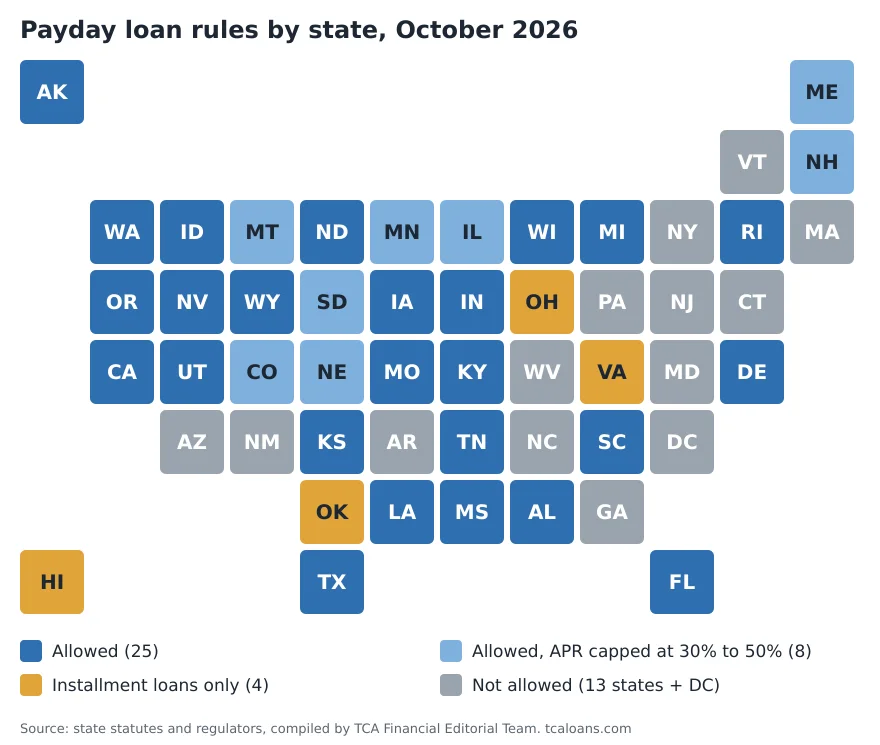
Short answer: As of October 2026, 25 states allow single-payment payday loans under their own rules on loan size, fees and rollovers. 8 more states license payday-style loans but cap the APR at 30% to 50%, which rules out typical payday pricing. 4 states allow only small installment loans, and 13 states plus the District of Columbia do not allow payday lending at all. The table below gives each state’s rules with a link to the statute and the regulator.
Key points
- Not allowed (13 states + DC): Arizona, Arkansas, Connecticut, District of Columbia, Georgia, Maryland, Massachusetts, New Jersey, New Mexico, New York, North Carolina, Pennsylvania, Vermont and West Virginia. These states either ban payday lending or set interest limits far below payday pricing.
- Allowed with an APR cap (8): Colorado, Illinois, Maine, Minnesota, Montana, Nebraska, New Hampshire and South Dakota. A cap of 36% (50% in Minnesota, 30% in Maine) rules out the usual fee of about $15 per $100 for two weeks (Maine also allows small fixed minimum charges).
- Installment loans only (4): Hawaii, Ohio, Oklahoma and Virginia. Single-payment loans were replaced by loans repaid over months.
- Allowed (25): Alabama, Alaska, California, Delaware, Florida, Idaho, Indiana, Iowa, Kansas, Kentucky, Louisiana, Michigan, Mississippi, Missouri, Nevada, North Dakota, Oregon, Rhode Island, South Carolina, Tennessee, Texas, Utah, Washington, Wisconsin and Wyoming. Most cap the loan at $500 to $1,000 and the fee at 10% to 20% of the amount, but Delaware, Idaho, Nevada, Texas, Utah and Wisconsin set no fee cap before maturity.
- Many states run a statewide database that lenders must check, so you cannot get around loan-count limits by going to another store.
What a payday loan costs at these caps
Payday fees look small because they are quoted per $100 for a few weeks. The APR shows the cost per year so you can compare it with other credit. The Consumer Financial Protection Bureau notes that a typical two-week payday loan with a $15 per $100 fee equals an APR of almost 400% (CFPB). Here is the math for a $300 request repaid in 14 days under several state fee caps:
| Fee rule | Cash received | Fee | APR (14 days) |
|---|---|---|---|
| $15 per $100 (common pricing, e.g. Kentucky cap) | $300 | $45.00 | 391% |
| 10% of the amount (Florida cap, before the verification fee) | $300 | $30.00 | 261% |
| 17.5% of the amount (Alabama cap) | $300 | $52.50 | 456% |
| 15% of a $300 check (California: $255 cash) | $255 | $45.00 | 460% |
Representative example: you borrow $300 and pay a $45 fee two weeks later, so you repay $345. That is an APR of about 391%. If you roll the loan over instead of repaying it, you pay another fee and still owe the $300. APR = fee / cash received x 365 / days x 100.
Payday loan laws by state: full table
Status and limits as written in each state’s law or published by its regulator, checked October 2026. “Max loan” is the most a borrower can have outstanding under the payday law, unless noted. “n/a” means the state has no payday product. Sources open in a new tab.
| State | Status | Max loan | Fee or rate cap | Key limits | Law and regulator |
|---|---|---|---|---|---|
| Alabama | Allowed | $500 | 17.5% of the amount advanced | 10 to 31 days; one renewal; $500 total outstanding; state database | Ala. Code §§ 5-18A-12, 5-18A-13 State regulator |
| Alaska | Allowed | $500 | $15 per $100 (or 15%) plus up to $5 origination fee | Minimum 14 days; max 2 renewals; $500 outstanding at once | Alaska Stat. §§ 06.50.410-06.50.470, 06.50.550 State regulator |
| Arizona | Not allowed | n/a | 36% on consumer loans of $3,000 or less | Payday law expired June 30, 2010 | A.R.S. § 6-632 State regulator |
| Arkansas | Not allowed | n/a | 17% per year (state constitution) | Storefront payday shut down after 2008 enforcement | Ark. Const. amend. 89, § 3 State regulator |
| California | Allowed | $300 check ($255 cash) | 15% of the check amount | Up to 31 days; no rollovers; one loan at a time per lender | Cal. Fin. Code §§ 23035-23037 State regulator |
| Colorado | Allowed, capped APR | $500 | 36% APR | Minimum 6-month term; one renewal; 30-day wait between loans | C.R.S. §§ 5-3.1-103, 5-3.1-105, 5-3.1-106, 5-3.1-108 State regulator |
| Connecticut | Not allowed | n/a | 36% APR on small loans | Unlicensed payday loans are void | Conn. Gen. Stat. § 36a-558(d)(1) State regulator |
| Delaware | Allowed | $1,000 | No rate cap in statute | Max 4 rollovers; 5 loans per 12 months; state database | 5 Del. C. §§ 2227(7)-(8), 2229, 2235A, 2235B State regulator |
| District of Columbia | Not allowed | n/a | 24% per year | Check cashers may not advance on post-dated checks | D.C. Code § 26-319(b) State regulator |
| Florida | Allowed | $500 | 10% of the amount plus a verification fee | 7 to 31 days; no rollovers; one loan at a time; 24-hour wait; state database | Fla. Stat. § 560.404 State regulator |
| Georgia | Not allowed | n/a | Payday lending prohibited | Installment lenders licensed separately | O.C.G.A. § 16-17-2 State regulator |
| Hawaii | Installment loans only | $1,500 | 36% interest plus $25 to $35 monthly fee; total charges max 50% of principal | 2 to 12 months; payday replaced Jan 1, 2022 | Haw. Rev. Stat. ch. 480J State regulator |
| Idaho | Allowed | $1,000 | No rate cap; fee per $100 must be posted | Max 3 renewals; loan max 25% of gross monthly income | Idaho Code §§ 28-46-412, 28-46-413, 28-46-414 State regulator |
| Illinois | Allowed, capped APR | n/a | 36% APR on all consumer loans | Predatory Loan Prevention Act, since March 23, 2021 | 815 ILCS 123/15-5-5 State regulator |
| Indiana | Allowed | $825 (inflation-adjusted from $550) | 15% of first $250, 13% up to $400, 10% above | Minimum 14 days; no renewals; 7-day wait after 6 loans in a row; database | Ind. Code §§ 37-3-2-10, 37-3-3-2, 37-3-3-5, 37-3-3-6, 37-3-3-8 State regulator |
| Iowa | Allowed | $500 | $15 on first $100, $10 per extra $100 | Up to 31 days; max 2 checks held; no refinancing | Iowa Code §§ 533D.9, 533D.10 State regulator |
| Kansas | Allowed | $500 | 15% of the amount advanced | 7 to 30 days; max 2 loans per lender; 3 loans in 30 days | K.S.A. 16a-2-404 State regulator |
| Kentucky | Allowed | $600 (since July 15, 2026) | $15 per $100 plus $3 database fee | 14 to 60 days; no rollovers; max 2 open loans; state database | KRS 286.9-010 et seq. State regulator |
| Louisiana | Allowed | $740 (Sept 1, 2026 to Aug 31, 2027) | 16.75% of the check amount | Up to 30 days; no rollovers; partial-payment option | La. R.S. 9:3578.1 et seq. State regulator |
| Maine | Allowed, capped APR | n/a | 30% per year (or small fixed minimum charges) | Typical payday pricing not permitted | 9-A M.R.S. §1-301(28-A) State regulator |
| Maryland | Not allowed | n/a | 33% per year on loans of $2,000 or less | Consumer Loan Law rate limits | Md. Code, Com. Law §12-306 State regulator |
| Massachusetts | Not allowed | n/a | 23% per year on small loans | Regulator: payday loans illegal because of APR | M.G.L. c. 140 §§96-114A State regulator |
| Michigan | Allowed | $600 | 15% of first $100, sliding down to 11%, plus database fee | Up to 31 days; no renewals; max 2 open loans; state database | MCL 487.2121 et seq. State regulator |
| Minnesota | Allowed, capped APR | $350 single payment | 50% APR all-in | Up to 30 days; ability-to-repay check above 36% APR | Minn. Stat. §47.60 State regulator |
| Mississippi | Allowed | $500 (fees included) | $20 per $100 (up to $250), $21.95 per $100 above | Up to 30 days; no renewals | Miss. Code Ann. §75-67-501 et seq. State regulator |
| Missouri | Allowed | $500 | Total interest and fees max 75% of the loan | 14 to 31 days; up to 6 renewals, each paying 5% of principal | RSMo §§408.500, 408.505, 408.506 State regulator |
| Montana | Allowed, capped APR | $300 | 36% per year | Up to 31 days; no renewals; one loan at a time | MCA 31-1-701 et seq. State regulator |
| Nebraska | Allowed, capped APR | $500 | 36% APR | Up to 34 days; no rollovers; max 2 checks held | Neb. Rev. Stat. §45-901 et seq. State regulator |
| Nevada | Allowed | 25% of gross monthly income | No rate cap in statute | Up to 35 days; all extensions end within 90 days; state database | NRS Chapter 604A State regulator |
| New Hampshire | Allowed, capped APR | $500 | 36% APR, no other fees | No renewals; no post-dated checks | RSA 399-A:17 State regulator |
| New Jersey | Not allowed | n/a | 30% per year criminal usury limit | Regulator: payday lenders unlicensed | N.J.S.A. 2C:21-19 State regulator |
| New Mexico | Not allowed | n/a | 36% APR (installments of 120+ days) | Since Jan 1, 2023 | NMSA 1978 §58-15-17 State regulator |
| New York | Not allowed | n/a | 16% civil, 25% criminal usury limit | Regulator: payday loans void | N.Y. Gen. Oblig. Law §5-501 State regulator |
| North Carolina | Not allowed | n/a | Consumer Finance Act rates (about 33% on smaller loans) | Payday authority expired Aug 31, 2001 | N.C.G.S. §53-281 State regulator |
| North Dakota | Allowed | $500 | 20% of the amount advanced | Up to 60 days incl. one renewal; $600 total; 3-business-day wait | N.D. Cent. Code ch. 13-08 State regulator |
| Ohio | Installment loans only | $1,000 | 28% interest plus fees; total cost max 60% of the loan | 91 days to 1 year; $2,500 total across lenders | Ohio Rev. Code 1321.35 to 1321.48 State regulator |
| Oklahoma | Installment loans only | $1,500 | 17% per month | 60 days to 12 months; payday loans ended Aug 1, 2020 | 59 O.S. §§ 3150-3150.27 State regulator |
| Oregon | Allowed | No set dollar cap | 36% interest plus one fee up to $30 (regulator: max 153.77% APR) | 31 to 60 days; max 2 renewals; 7-day wait | ORS 725A.010 to 725A.092 State regulator |
| Pennsylvania | Not allowed | n/a | 6% per year usury limit | No payday licensing law | 41 P.S. § 201 State regulator |
| Rhode Island | Allowed | $500 | 10% of the amount advanced | Min 13 days; one rollover; payday authority repealed Jan 1, 2027 | R.I. Gen. Laws §§ 19-14.4-4, 19-14.4-5.1 State regulator |
| South Carolina | Allowed | $550 | 15% of the amount advanced | Up to 31 days; no renewals; one loan at a time; state database | S.C. Code Ann. Title 34, Chapter 39 State regulator |
| South Dakota | Allowed, capped APR | n/a | 36% APR all-in | Voter-approved cap, 2016 | SDCL 54-4-44 State regulator |
| Tennessee | Allowed | $500 check (fee included) | 15% of the check amount | Up to 31 days; no renewals; max 3 open loans | Tenn. Code Ann. 45-17-101 et seq. State regulator |
| Texas | Allowed | No set dollar cap | No cap on the credit access business fee | Loans arranged by licensed CSO/CAB brokers; city rules may add limits | Tex. Fin. Code ch. 393, Subch. G State regulator |
| Utah | Allowed | No set dollar cap | No rate cap in statute | No interest after 10 weeks; free cancellation by next business day | Utah Code Title 7, Chapter 23 State regulator |
| Vermont | Not allowed | n/a | 18% per year on single-payment loans | Lenders must be licensed | 9 V.S.A. 41a State regulator |
| Virginia | Installment loans only | $2,500 | 36% interest plus monthly fee up to $25 | 4 to 24 months; one loan at a time; state database | Va. Code §§ 6.2-1800 et seq. State regulator |
| Washington | Allowed | $700 (or 30% of gross monthly income) | 15% of first $500, 10% above | Up to 45 days; 8 loans per 12 months; state database | RCW 31.45 State regulator |
| West Virginia | Not allowed | n/a | 31% per year on loans of $3,500 or less | Regulator: payday lenders generally prohibited | W. Va. Code § 32A-3-1(b) State regulator |
| Wisconsin | Allowed | $1,500 (or 35% of gross monthly income) | No rate cap before maturity | Up to 90 days; one rollover; state database | Wis. Stat. § 138.14 State regulator |
| Wyoming | Allowed | No set dollar cap | Greater of $30 or 20% per month | Up to 1 month; no refinancing with a new loan | Wyo. Stat. §§ 40-14-362 through 40-14-368 State regulator |
How to read the rules
- Fee or rate cap: the most a lender can charge. A fee of 15% of the amount on a two-week loan is not 15% a year; see the APR table above.
- Rollover or renewal: paying only the fee to push the due date back. Each rollover adds a new fee. Many states ban or limit rollovers.
- Cooling-off period: a required wait after repaying one loan before taking the next (for example 24 hours in Florida, 7 days in Oregon).
- Loan limits and databases: caps on how many loans you can have at once (one in Florida and South Carolina, two in Michigan and Kentucky) enforced through a statewide database.
- Right to cancel: several states, including Michigan, Missouri, North Dakota, Utah and Wisconsin, let you cancel at no cost by the next business day if you return the money.
Recent changes to watch
- Kentucky: 2026 SB 219, effective July 15, 2026, raised the total limit from $500 to $600, with yearly inflation updates up to $850, and made the $3 database fee chargeable to the borrower.
- Louisiana: Act 510 of 2025 raised the deferred presentment amount to $700 and added yearly inflation updates. The regulator lists $740 for Sept 1, 2026 to Aug 31, 2027.
- Rhode Island: a 2025 law repeals the payday (deferred deposit) authority on January 1, 2027.
- Indiana: the small loan law moved from IC 24-4.5-7 to IC 37-3 in 2026 without changing its substance.
- Minnesota (2023) set an all-in 50% APR cap, and New Mexico moved to a 36% cap on January 1, 2023.
Online lenders and your state’s law
State payday rules protect residents of that state, and several states require online lenders to hold a state license before lending to their residents (for example Tennessee and Vermont). Regulators in states such as Connecticut and New York say payday loans made in violation of their laws are void. If an online lender is not licensed in your state, contact your state regulator before you sign anything.
Active-duty service members and their dependents have an extra federal protection: the Military Lending Act caps the Military Annual Percentage Rate at 36% on payday and other consumer loans (10 U.S.C. 987; CFPB).
How to check a lender before you borrow
- Look up the lender on your state regulator’s license search (the regulator links are in the table) or on NMLS Consumer Access.
- Read the APR, the fee in dollars, the due date and the rollover rules in the loan agreement before you sign. Lenders must show you the APR before you agree.
- Compare the cost with other options, such as a payment plan with the bill you need to cover, a credit union loan or help from family.
- If something goes wrong, file a complaint with your state regulator and with the CFPB.
Where TCA Financial’s service is available
Residents of Arkansas, New York, Vermont and West Virginia are not eligible to use this website or service, and residents of some other states may not be eligible for some or all short-term, small-dollar loans. If you live in a state where these loans are allowed and want to see what participating lenders may offer, you can submit a request. Submitting a request is free and you are under no obligation to accept an offer. Approval is not guaranteed, and the lender, not TCA Financial, sets your rate and terms.
Frequently asked questions
Which states have banned payday loans?
Arizona, Arkansas, Connecticut, District of Columbia, Georgia, Maryland, Massachusetts, New Jersey, New Mexico, New York, North Carolina, Pennsylvania, Vermont and West Virginia do not allow payday lending. In Colorado, Illinois, Maine, Minnesota, Montana, Nebraska, New Hampshire and South Dakota, payday-style loans are licensed but APR caps of 30% to 50% rule out typical payday fees.
How many payday loans can you have at once?
It depends on the state. Florida and South Carolina allow one outstanding loan, Kentucky and Michigan allow two in total, and Washington limits borrowers to eight loans in any 12 months. Lenders check a statewide database in these states.
What is the most you can borrow with a payday loan?
Most states that allow payday loans cap them between $500 and $1,000. Indiana’s inflation-adjusted cap is $825, Wisconsin’s is $1,500 or 35% of gross monthly income, and Nevada, Texas, Utah and Wyoming set no fixed dollar cap.
Are online payday loans legal in my state?
The same state rules apply to online loans made to residents of that state. If payday loans are not allowed where you live, a licensed lender should not offer you one. Check the lender’s license with your regulator.
Can a payday lender roll over my loan?
Many states ban rollovers (for example California, Florida, Indiana, Kentucky, Michigan and South Carolina). Others allow a limited number, such as one in Alabama and Rhode Island, two in Alaska and Oregon, three in Idaho and four in Delaware.
Related guides
- Payday loans: pros and cons of getting one
- Are payday loans worth the cost?
- Does filing bankruptcy remove payday loan debt?
Sources
Every state row links to the state statute and the state regulator page used for this guide. Federal sources: CFPB, What is a payday loan?; CFPB, What are the costs and fees for a payday loan?; 10 U.S.C. 987 (Military Lending Act). Last reviewed October 25, 2026 by the TCA Financial Editorial Team. Found an outdated rule? Email support@tcaloans.com.